Head office raises a store’s target midway through the period. The store team expects its bonus to be calculated against the original target, while HR uses the revised figure. Returns may then produce two different calculations for the same period.
The basis for the bonus
The starting point is the employment contract, the bonus policy and established workplace practice. Authority to set targets does not automatically validate every change; equally, not every target update constitutes a material change. The existing bonus conditions and the effect of the change must be examined together.
Written notification and acceptance
Under Article 22 of the Turkish Labour Act, a material change to the employee’s detriment must be notified in writing. A change not accepted by the employee in writing within six working days is not binding. Changes cannot operate retroactively. Applying a change only to a future period does not dispense with this written process. When a particular bonus is earned depends on the applicable bonus conditions.
Court decisions and their scope
The 9th Civil Chamber of the Court of Cassation treated the subsequent introduction of performance criteria for an unconditionally paid bonus as a material adverse change (2015/20587 E., 2018/13156 K., 18 June 2018). That decision does not directly concern a mid-period target increase. The 22nd Civil Chamber’s decision 2017/12618 E., 2018/10746 K., dated 4 May 2018, addresses regular bonuses as an established employment condition and the examination of relevant records in calculating bonuses.
Returns and the calculation
The effect of a return on a bonus also depends on the applicable bonus conditions. A return entry should not, by itself, be treated as an automatic ground for deduction. Recording in advance which employee receives credit for a sale and which period a return affects makes the calculation easier to verify later.
Records to review
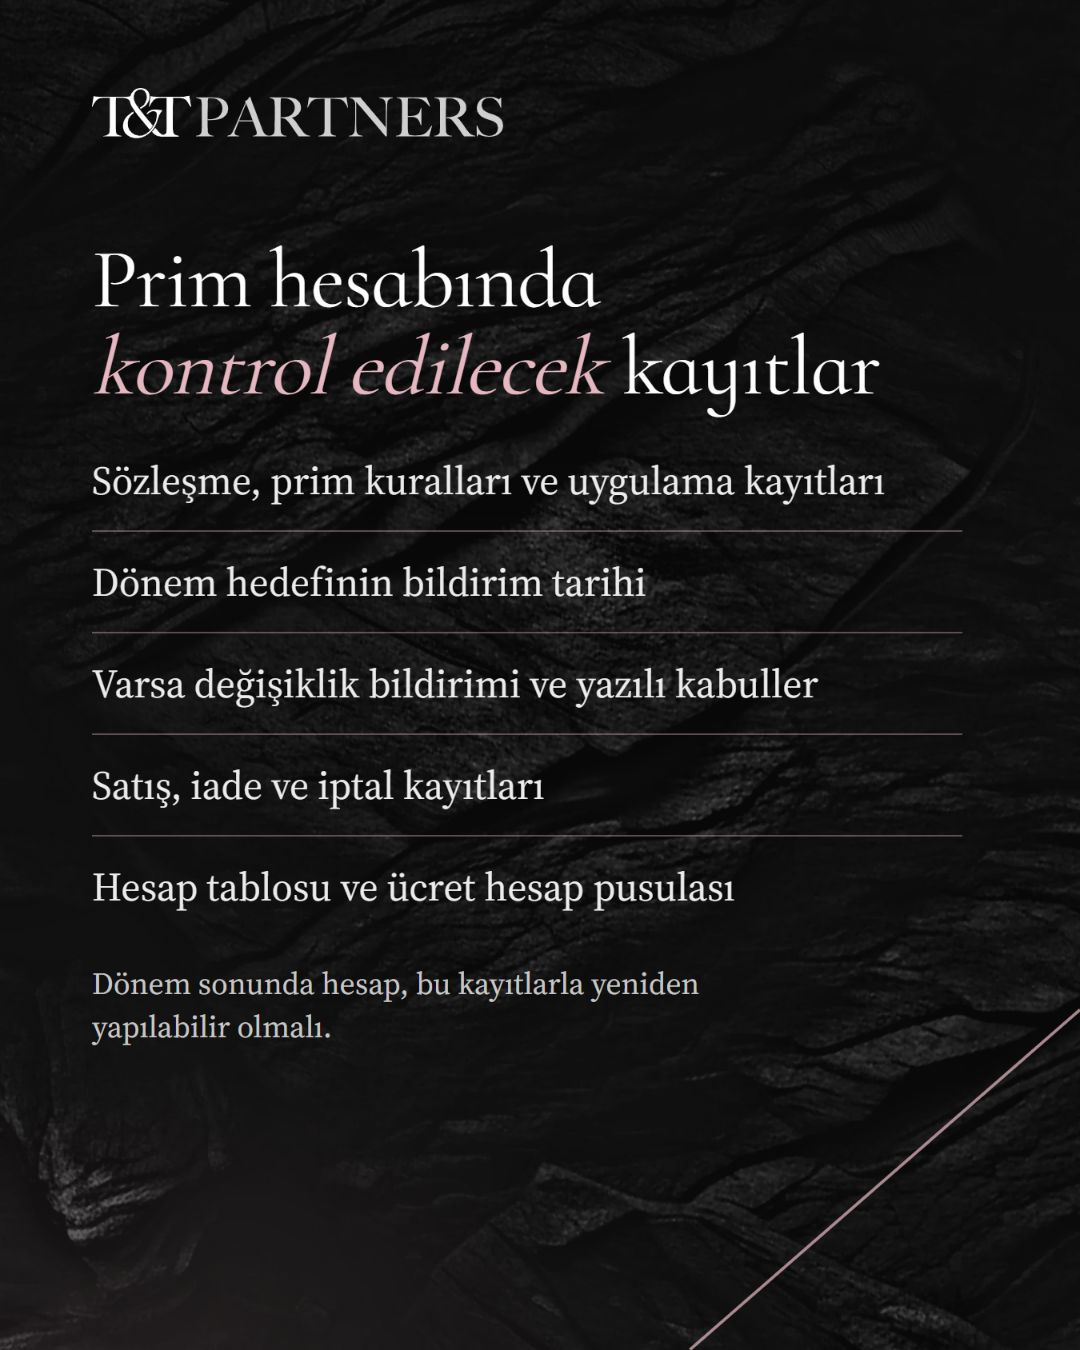
Target notices, any change and written acceptance documents, sales and return records, calculation sheets and itemised wage statements should be reviewed together.
Sources
- Turkish Labour Act No. 4857, Articles 22, 32 and 37
- Yargıtay 9. HD: 2015/20587 E., 2018/13156 K., 18.06.2018; 22. HD: 2017/12618 E., 2018/10746 K., 04.05.2018
General information only; assessment depends on the applicable bonus conditions.